

The nightmare of the sovereign debt crisis is returning to European bond markets.
Not in the guise of the dramatic 2010–2012 turmoil and existential threats of Eurozone fragmentation, but through an alternative mechanism: higher interest rates, more expensive debt servicing, sluggish economic growth, and mounting difficulties for governments attempting to convince investors that they can anchor their public finances.
At the epicenter stand two of the largest economies in the Eurozone: France and Italy.
France currently represents the most acute case.
The French Ministry of Economy and Finance forecasts that public debt will surge to 119.3% of GDP in 2026, up from 115.7% in 2025, and will continue climbing to 121.7% in 2027.
In 2019, prior to the pandemic, the corresponding ratio stood below 100% of GDP.
Concurrently, the French fiscal deficit is projected to close 2026 at 5.4% of GDP, despite administrative efforts to rein it in. Prime Minister Sébastien Lecornu has announced a 54 billion euro expenditure-cutting package for the 2027 budget in an attempt to stem the deterioration. The core obstacle is that spending cuts must pass through a deeply fractured parliament at a time when public anger over the cost of living continues to mount.
And sovereign bond markets have already sent their warning shot.
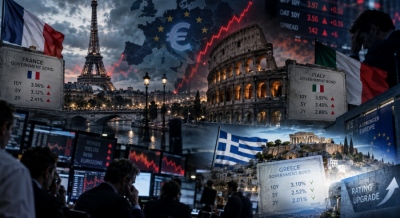
On Friday (September 18), the 10-year French sovereign spread over the German Bund exceeded one percentage point, a threshold unseen since the height of the Eurozone debt crisis.


The yield on the French 10-year benchmark climbed to roughly 4.46%, as investors demand higher premia to hold French paper.
Italy carries larger debt, but a smaller fiscal deficit
The picture for Italy presents a different, and perhaps even more intriguing, profile.
Rome navigates this period carrying a much larger overall stock of liabilities.
Public debt is anticipated to touch nearly 139% of GDP in 2026, a level that, according to Minister of Economy and Finance Giancarlo Giorgetti, will render Italy the most indebted sovereign in the Eurozone, overtaking Greece.
He cautioned on September 18 that debt servicing expenditures are expanding at an «alarming pace».
Nonetheless, a fundamental divergence from France persists: the Italian fiscal deficit remains considerably lower.
Rome is targeting a budget shortfall below 3% of GDP, aiming to secure an early exit from the European Union's Excessive Deficit Procedure.
This illustrates that market participants are not merely reacting to absolute debt-to-GDP levels.
They are simultaneously assessing deficit trajectories, baseline growth, refinancing costs, and the capability of each administration to articulate a credible medium-term fiscal adjustment path.
Even so, Italian borrowing costs continue to climb. At a recent auction, the 3-year BTP yield touched 3.43%, reaching highs unseen since June 2024, while the 7-year paper cleared at 3.98%, the highest mark since November 2023.
The shared vulnerability: More expensive capital
The common denominator binding France and Italy is not merely high indebtedness.
It is that both sovereigns are facing rising costs of capital against a backdrop of subdued economic expansion.
Germany, which serves as the risk-free benchmark across the Eurozone sovereign debt universe, saw the 10-year Bund yield hit 3.57% on September 15, its highest level since June 2009. Even after a slight retreat, the German benchmark hovered around 3.50%.
This upward repricing carries acute consequences for highly leveraged sovereigns.
The higher the yield at which maturing debt rolls over, the greater the compounding interest burden weighing on national budgets.
Furthermore, the macroeconomic climate could deteriorate further should energy commodities remain elevated. Markets have ramped up expectations for additional rate hikes by the ECB following rallies in energy prices, even as ECB Vice President Boris Vujčić emphasized that monetary authorities must evaluate broader economic metrics rather than reacting solely to volatility in crude oil and natural gas.

Not yet 2011, but markets are baring their teeth
The prevailing dynamic differs markedly from the systemic debt crisis of the previous decade.
The Eurozone now fields enhanced institutional backstops and crisis mechanisms, while the ECB maintains liquidity and anti-fragmentation toolkits that did not exist during the earlier turmoil.
That does not mean, however, that the predicament is minor.
The crux of current market pressure is that the era of «free money» has conclusively ended. Sovereigns must now refinance immense debt piles in an environment where investors demand elevated real yields.
France confronts the necessity of steep austerity while running a deficit above 5% of GDP. Italy shoulders an even heavier debt overhang and watches debt service costs climb.
Lurking behind both is a third structural variable: economic growth.
The lower the nominal growth rate of an economy relative to the sovereign borrowing cost, the more arduous stabilizing debt-to-GDP dynamics becomes.
Thus, the unfolding test for Southern Europe is not necessarily a sudden 2012-style crisis. It is a more gradual and persistent drag: the return of debt service costs as the primary constraint on fiscal policy.
Crucially, the challenge is no longer restricted to the periphery. The surge in sovereign bond yields has evolved into a continent-wide and global phenomenon. The difference is that countries already carrying massive balance-sheet debt have far narrower buffers to absorb the shock.
France sees this unfolding directly in its widening spread.
Italy registers it across rising debt-servicing outlays.
The question for financial markets is not whether Europe is reliving 2011, but how long governments can navigate debt burdens of 120% to 140% of GDP when capital is no longer cheap.
Double upgrade from Moody's and Scope Ratings cushions Greece
Highlighting Greece's new credit rating milestone, convergence with Italy, and the rating agencies' verdict on debt reduction and primary surpluses, a report by Bloomberg broke down the impact of the dual rating upgrades from Moody's Ratings and Scope Ratings.
According to the agency, Greece secured a double boost to its sovereign credit profile, reaching rating parity with Italy at Scope Ratings.
Scope Ratings upgraded Greece to BBB+, placing it on the identical credit tier as Italy.
This represents the highest credit rating currently assigned to Greece by any major rating agency.
Simultaneously, Moody's Ratings upgraded the outlook on the Greek sovereign to positive, while maintaining its investment-grade rating at Baa3, the baseline tier of investment grade.

Debt trajectory and primary surpluses drive the upgrade
According to Scope Ratings, the upgrade reflects the swift decline in the public debt-to-GDP ratio and strengthening fiscal sustainability.
A decisive factor is the uniquely favorable profile of Greek sovereign debt, the vast majority of which is held by official lenders in the public sector, insulating it from the immediate vagaries of private market sentiment.
Scope Ratings underscored that high, sustainable primary surpluses, structural enhancements in tax collection and compliance, and a sustained track record of prudent fiscal execution played pivotal roles.
For its part, Moody's Ratings identified expanding evidence that Athens' persistent adherence to structural economic and institutional reforms is yielding tangible dividends, reinforcing the resilience of the real economy and public finances beyond earlier baseline projections.
The two announcements mark another milestone in the rehabilitation of Greece's status in global capital markets, further closing the chapter on the bailout era.
Greek debt ratio set to fall below Italy's
The pace of fiscal consolidation in Greece has advanced so rapidly that the country is projected to bring its debt-to-GDP ratio below that of Italy during 2026.
Under that scenario, Italy will assume the mantle of carrying the highest public debt ratio among major European economies.
Greek yields drop below France, Italy, and the US
This structural transformation is visibly reflected across secondary sovereign bond markets.
Yields on Greek government bonds are trading below those of France, Italy, and the United States.
Greece stands out on the European periphery for outperforming fiscal targets at a juncture when bondholders are growing increasingly anxious regarding the fiscal trajectories of core economies.
On Friday (September 18), a key benchmark tracking French sovereign credit risk breached a milestone level for the first time in 14 years.
Simultaneously, the Greek economy continues to expand at a faster clip than many European peers, while government primary surpluses (which exclude interest outlays) consistently outstrip budgeted targets.
Early debt repayments of 13 billion euros
Stronger fiscal performance enables Athens to proceed with accelerated early repayments to official creditors.
The Ministry of National Economy and Finance plans to pay down roughly 13 billion euros in legacy bailout loans during 2026, sustaining similar early redemption tranches over subsequent years.
This prepayments strategy constitutes a central pillar of the push to accelerate debt reduction and bolster sovereign credit ratings further.
However, Greece does not constitute a tranquil oasis shielded from the Eurozone tempest, regardless of governmental assurances.
The domestic economy remains fragile and burdened by low total factor productivity; even a modest external shock could disrupt recent growth gains.
www.bankingnews.gr


Σχόλια αναγνωστών